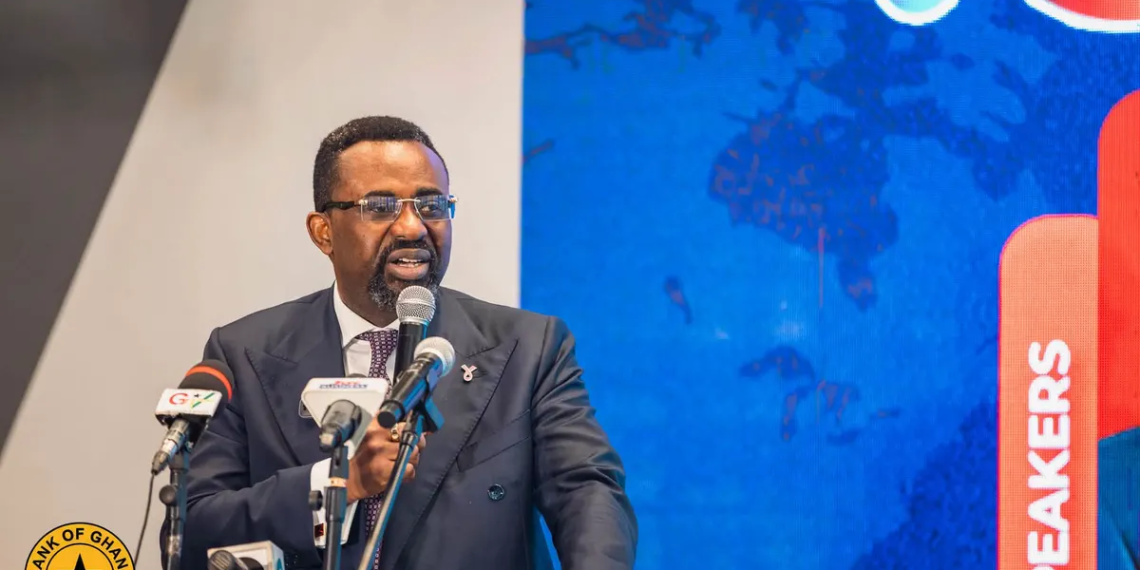
Bank of Ghana Governor Dr Johnson Pandit Asiama has outlined four key priorities for the future of digital payments in Sub-Saharan Africa, calling for cheaper cross-border transactions, improved financial inclusion, stronger consumer protection and harmonised fintech regulations.
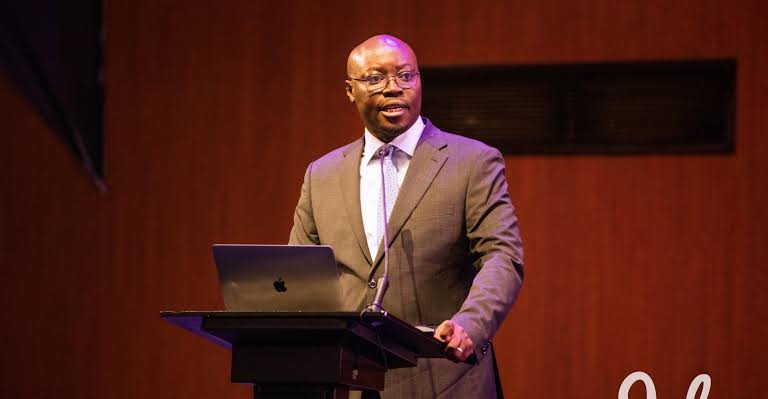
Speaking at the Joint AFR-MCM High-Level Event on Digital Innovations in Payments during the ongoing World Bank and IMF Annual Meetings in Bangkok, Thailand, Dr Asiama said the focus must shift from expanding digital payment adoption to ensuring that the systems deliver real benefits to individuals, businesses and national economies.
His remarks come as Ghana’s mobile money industry continues to record significant growth. Transactions exceeded one billion in a single month for the first time in August 2026, with the total value reaching GH¢519 billion, representing a 46.5 per cent increase compared with the same period a year earlier.
The Governor said the growing adoption of digital payments had settled the question of whether Africans were ready to embrace the technology. The priority now, he explained, was to ensure that the expansion translated into greater efficiency, financial inclusion and stability across the region.
“The question before us now is how to ensure that this scale delivers efficiency, inclusion and stability across the region,” he told fellow central bank governors and representatives of the International Monetary Fund.
Dr Asiama identified affordable cross-border payments as his first priority, arguing that the benefits of digital finance would remain limited if transferring money between African countries continued to be expensive.
Despite the growth of mobile money and digital wallets, many cross-border transactions still pass through correspondent banks outside the continent, increasing processing times, foreign exchange costs and intermediary charges. The cost of sending money across borders in Africa remains above 8 per cent, compared with an international target of 3 per cent.
He said reducing these charges would support small businesses, traders and families while strengthening regional commerce under the African Continental Free Trade Area.
Ghana is pursuing cross-border payment interoperability through the Ghana–Rwanda and Ghana–Nigeria corridors, testing connections involving central bank digital currencies, stablecoins, bank accounts and mobile wallets. The Bank of Ghana has also extended the Pan-African Payment and Settlement System (PAPSS) to mobile wallets along the Ghana–Nigeria corridor.
Dr Asiama stressed the need to build on existing infrastructure rather than establish additional platforms that cannot communicate with one another. He said the ultimate goal was to move beyond pilot projects and provide services that consumers and businesses could use in their daily transactions.
His second priority is to move financial inclusion beyond account ownership to meaningful participation in the financial system.
Although 81 per cent of adults in Ghana have access to financial services, the figure drops to 52.7 per cent when actual usage and service quality are considered. Private-sector credit also remains at approximately 10 per cent of gross domestic product, highlighting the gap between widespread access to payment services and the availability of productive financing.
“Digital rails must now support responsible savings, credit, insurance and investment,” Dr Asiama said.
The Bank of Ghana is seeking to address this gap through its Digital Credit Service Provider framework, which brings digital lenders under formal supervision. It is also developing systems to improve visibility into borrowers’ total loan exposures and reduce the risk of customers accumulating multiple debts across different lending platforms.
The Governor said open banking was another important part of the strategy. The initiative is moving from proof of concept to a pilot and could allow customers to authorise regulated providers to access their financial data and offer more competitive services.
With appropriate consent and data-protection safeguards, the initiative could help smaller financial institutions assess customers who lack traditional collateral or extensive banking histories.
Dr Asiama’s third priority is strengthening public confidence in digital financial services amid rising fraud concerns.
Reported fraud cases in Ghana increased by 48 per cent in 2025, with the increase occurring almost entirely among payment service providers, although the total value at risk remained broadly unchanged.
The Bank’s response includes consumer education, confirmation of recipients’ identities before payments and stronger controls over SIM replacements. These measures are intended to reduce fraudulent transactions and protect customers from losses.
The central bank is also strengthening cybersecurity through its revised Cyber and Information Security Directive and expanding the Financial Industry Command Security Operations Centre beyond universal banks. Further guidance on artificial intelligence is expected to address emerging risks associated with increasingly autonomous systems, including agentic AI.
Dr Asiama said digital payment systems must remain secure and reliable if public confidence is to be sustained. Without effective safeguards and avenues for redress, rising fraud could undermine the gains made through digital financial services.
His fourth priority is reducing regulatory fragmentation, which often forces fintech companies to repeat licensing procedures whenever they enter a new African market.
Ghana is pursuing a Licence Passporting Framework with the National Bank of Rwanda to make it easier for regulated financial technology firms to expand across participating jurisdictions. More than 10 countries are being engaged to join the initiative.
The framework could reduce compliance costs and encourage fintech companies to operate across borders, although its success will depend on regulators agreeing on sufficiently consistent standards for supervision, consumer protection and enforcement.
Dr Asiama also called for common standards for payment messaging, confirmation of payees and fraud-data sharing to improve interoperability and close gaps that criminals could exploit across jurisdictions.
The Bank of Ghana has offered to share its experience in payment interoperability, licence passporting and the Financial Industry Command Security Operations Centre model with other African regulators.
The Governor maintained that central banks should focus on establishing the right conditions for innovation rather than deciding which technology should dominate the market.
“Central banks should not determine which technology succeeds,” he said. “Our role is to ensure that emerging systems are safe, efficient, resilient and inclusive.”
The position reflects the Bank’s approach of allowing different technologies to compete while ensuring that they meet essential standards for security, affordability and financial stability.
Ghana’s achievement of more than one billion mobile money transactions in a month demonstrates the scale digital finance has reached. The next challenge will be to translate that growth into cheaper cross-border transfers, wider access to responsible credit and stronger protection for consumers.