Ghana’s efforts to rebuild its microfinance sector must go beyond increasing capital requirements, with stronger governance, effective supervision and customer protection needed to prevent further institutional failures.
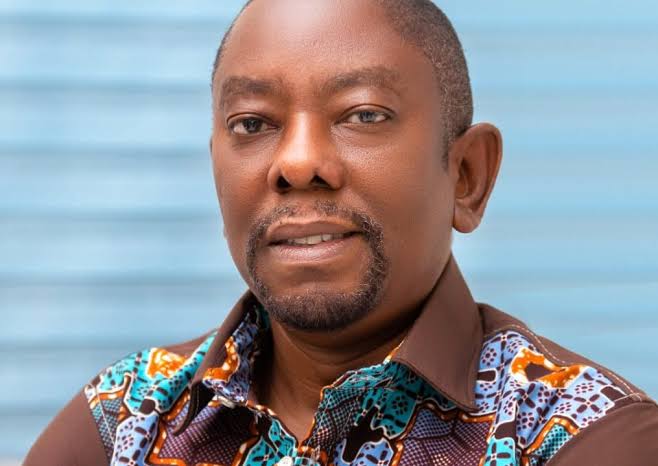
Reverend Dr Daniel Agbeko, Senior Lecturer and Head of the Department of Multidisciplinary Studies at Ho Technical University, has warned that without these measures, recapitalisation alone may fail to address the problems that continue to put customers’ savings at risk.
Speaking at the 2026 Annual General Meeting of the Micro-Credit Association Ghana in Ho, Dr Agbeko said the revised Bank of Ghana framework offered an opportunity to improve accountability, strengthen risk management and build a more sustainable microfinance industry.
Microfinance institutions play an important role in Ghana’s economy by providing financial services to traders, farmers, transport operators and small businesses that often struggle to access credit from conventional banks. However, when these institutions collapse, customers can lose their savings, business capital and money set aside for school fees, healthcare and other essential needs.
Although inadequate capital can leave institutions vulnerable to financial shocks, Dr Agbeko’s concerns point to a deeper problem: weak governance. An institution may meet the required capital threshold and still face collapse if its directors misuse funds, managers issue risky loans to connected parties or internal controls fail to detect financial irregularities.
This makes good governance just as important as recapitalisation. Without competent leadership, transparent reporting and effective internal controls, additional capital could simply expose customers to greater losses.
Another key issue is the Bank of Ghana’s proposed approach to delegated supervision. Under this arrangement, certain monitoring responsibilities could be assigned to competent bodies operating under the regulator’s standards and oversight.
Dr Agbeko believes the approach could improve the frequency of inspections, strengthen early-warning systems and make supervision more accessible to institutions operating outside major commercial centres.
Effective monitoring could help identify problems such as worsening loan portfolios, liquidity shortages, governance disputes and inaccurate financial reporting before they threaten an institution’s survival.
However, he cautioned that delegated supervision must be supported by clear mandates, competent personnel, reliable information systems and effective enforcement mechanisms. Without these safeguards, conflicts of interest could undermine the process, particularly if supervisory bodies are reluctant to sanction institutions within their own membership.
The Bank of Ghana must therefore retain ultimate responsibility for regulatory enforcement, including major sanctions, licensing decisions and the resolution of failing institutions. Supervisory bodies should also operate under clear reporting deadlines, audit requirements and conflict-of-interest rules.
For customers, the success of the reforms will depend on whether they receive better protection in their everyday dealings with financial institutions.
Borrowers need clear information about interest rates, fees, penalties and the full cost of loans before signing agreements. Institutions must also avoid abusive debt-collection practices and ensure that customers’ personal information is handled responsibly.
Depositors, meanwhile, need accurate account records, accessible complaint channels and clear information about how to report misconduct. Publishing complaint statistics and enforcement outcomes could also help the public identify institutions that repeatedly breach regulatory requirements.
The growing use of digital lending and mobile repayment platforms presents additional challenges. While technology can lower costs and extend financial services to underserved communities, it also raises concerns about cybersecurity, data privacy, irresponsible lending and excessive borrowing.
Financial institutions must ensure that technology improves service delivery without weakening accountability. Regulators should also encourage clearer disclosure of borrowing costs, including processing fees, compulsory savings and other charges that can make loans more expensive than advertised.
The industry is also facing pressure to meet new capital requirements and the December 31 compliance deadline. While stronger standards are necessary, the implementation process must consider the risk that sudden closures or consolidation could leave some communities with fewer financial service providers.
Institutions that cannot meet the requirements should be given clear guidance on their options, including mergers where appropriate. Those leaving deposit-taking activities must also ensure that customers’ balances are properly reconciled and their obligations addressed.
At the same time, supervision should reflect the different risks posed by institutions. A small non-deposit-taking lender does not present the same level of risk to public savings as a large institution holding substantial customer deposits. Requirements should therefore be proportionate to the size, activities and risk profile of each operator.
MCAG Board Chairman Benjamin Tuckson Jr also stressed the need for the industry to embrace reform, invest in its workforce, adopt appropriate technology and maintain high standards of governance and consumer protection.
“The reputation of the industry is collective,” he said, calling for stronger cooperation among operators, regulators and the association.
Ultimately, Ghana’s microfinance reforms must be judged by whether institutions become safer for the people who depend on them. Meeting capital requirements and complying with new regulations will mean little if weak leadership and poor oversight continue to put customers’ money at risk.
Stronger governance, credible supervision and meaningful consumer protection must therefore go hand in hand with recapitalisation. For the traders, farmers and small businesses that rely on microfinance, the real measure of success is whether they can save and borrow with confidence.