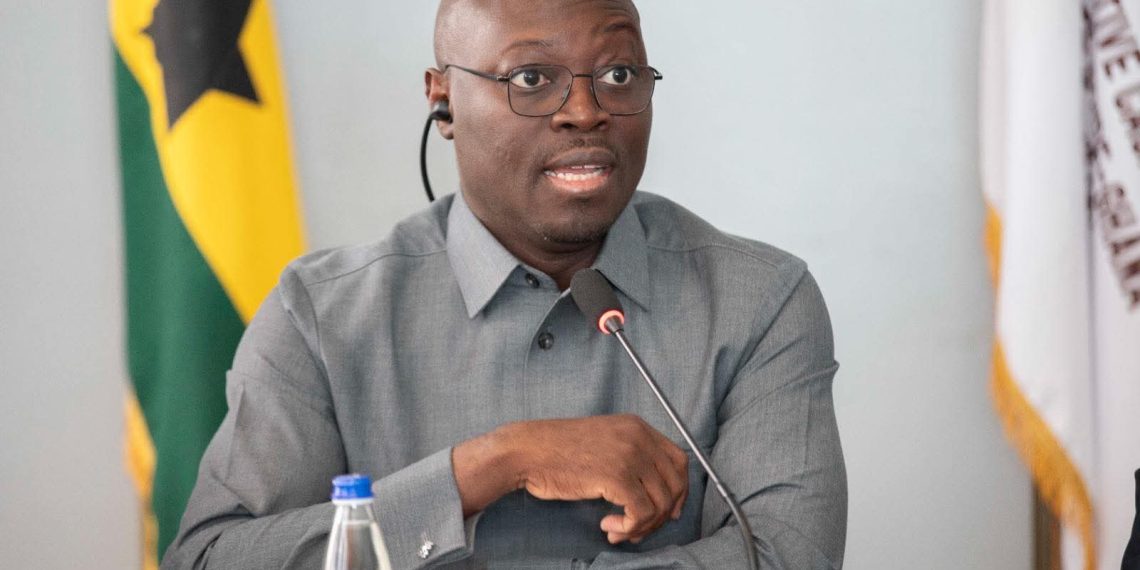
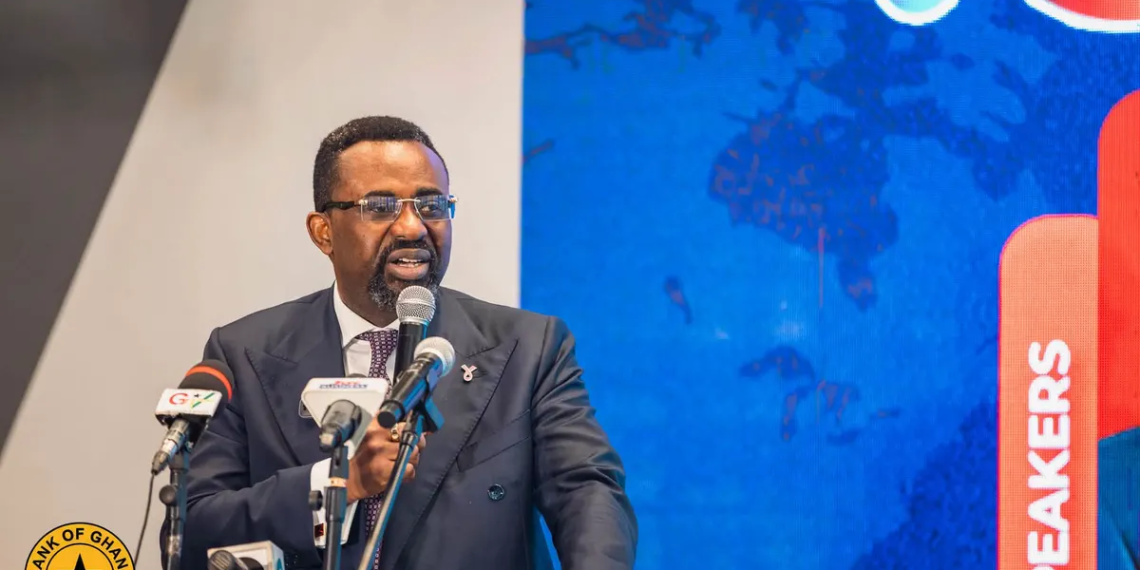
Bank of Ghana Governor Dr Johnson Pandit Asiama has urged commercial banks to strengthen their risk-management systems, corporate governance and fraud controls as the banking sector continues to recover.
He said improvements in capital positions, financial stability and non-performing loans were encouraging, but warned banks against becoming complacent. According to him, sustaining the gains will require institutions that can withstand economic shocks while adapting to technological and market changes.
Dr Asiama made the remarks at the 43rd Annual General Meeting of the Ghana Association of Banks and the launch of the sixth edition of the Ghana Bankers’ Voice Magazine in Accra on October 8.
“Our ambition should be to build a banking sector that is strong enough to absorb shocks, innovative enough to adapt to change, and capable of financing Ghana’s long-term economic transformation,” he said.
His warning comes as lending to the private sector gathers pace, raising expectations that businesses could gain better access to financing. Private-sector credit grew by 35.5 per cent in August 2026, compared with 13.3 per cent during the same period in 2025. In real terms, growth accelerated to 29 per cent from 1.7 per cent a year earlier.
The increase in lending coincided with a decline in the average lending rate to 15.9 per cent in August 2026 from 24.2 per cent in August 2025, alongside improving demand for credit.
While the trend could support business expansion and economic activity, rapid lending growth also increases the need for careful borrower assessment. Banks that relax lending standards to take advantage of rising demand risk accumulating bad loans if borrowers cannot meet their repayment obligations.
To address these concerns, the Bank of Ghana is preparing a credit-risk management directive to strengthen the rules governing loan assessment, administration, monitoring and recovery.
The central bank is also developing a Liquidity Coverage Ratio directive that will require banks to maintain sufficient high-quality liquid assets to withstand a severe liquidity shock lasting 30 days.
The proposed measures are intended to ensure that banks remain prepared for financial stress even when economic conditions appear favourable. The regulator has also asked banks to address weaknesses identified through its macroprudential stress tests and improve their fraud prevention, cybersecurity and liquidity-management systems.
Dr Asiama noted that digitalisation had improved access to financial services and reduced transaction costs, but it had also exposed banks to growing threats, including cyberattacks, identity theft, payment fraud and operational disruptions.
As a result, banks must look beyond traditional credit risks and strengthen their ability to manage liquidity, foreign-exchange, technological and reputational risks.
The BoG has also directed financial institutions to ensure that fraud-control units have direct and unrestricted access to managing directors or chief executives. The measure is intended to protect the independence of investigations and prevent serious fraud cases from being obstructed or weakened by middle management.
The Governor’s message also places responsibility on bank boards and senior executives to make risk management central to business decisions. This includes setting lending targets, investing in technology, designing staff incentives and determining how quickly institutions expand into new products and markets.
The warning comes as banks rebuild following the impact of Ghana’s domestic debt restructuring and pursue new sources of income. Although stronger capital positions provide a buffer against losses, they cannot fully protect institutions from poor lending decisions, weak governance or inadequate operational controls.
The Bank of Ghana says it will continue working with banks and other stakeholders to build a resilient, innovative and sustainable financial system capable of supporting the country’s economic development.
The challenge for the industry will be to sustain the recovery, expand credit to productive businesses and maintain sound lending standards to prevent a fresh rise in non-performing loans.